Search Results for 'return model'
return model published presentations and documents on DocSlides.
Return-Current Losses and their Impact on Solar Flare Emissions
by ellena-manuel
The return current neutralizes the current carrie...

Return and Risk: The Capital Asset Pricing Model (CAPM)
by lauren
Module 5.4. Equilibrium risk pricing. Modules 2 an...
The Arbitrage Pricing Theory and Multifactor Models of Risk
by pamella-moone
P.V. . Viswanath. For a First Course in . INvestm...
Chapter 9 Capital Asset Pricing Model and Beta Forecasting
by min-jolicoeur
By. Cheng Few Lee. Joseph . Finnerty. John Lee. A...

Achieving a long-run equilibrium in the dynamic GTAP
by min-jolicoeur
model. Organised session 21, Trade Projections. 2...

This study aims to establish a valuation model based on the fair price
by esther
BVS book value of equity per share k equity ch...
Model of gene transcription including the return of a RNA p
by pamella-moone
to the beginning of a transcriptional cycle. Vlad...


1 A single-factor security market
by natalia-silvester
The single-index model. Estimating the single-ind...
Company analysis and stock valuation
by danika-pritchard
ch14. Company Analysis vs. Stock Valuation. Good ...


China daily Extreme precipitation GEV fitting
by phoebe-click
Jun Sun . Fuqing. Zhang. outline. Data. Method. ...
Risk Parity, A Novel Approach To Asset Allocation
by danika-pritchard
Ken . Shaw. Envestnet. | PMC. Paul Brennan. Firs...
Computational Finance Applications in Investment Management
by alida-meadow
Prepared by John . Lafare. Vice President & D...
Chapter 11 Optimal Portfolio Choice and the Capital Asset Pricing Model
by tatiana-dople
Chapter Outline. 11.1 . The Expected Return of a...

Innovation in Developmental Education:
by jane-oiler
You Can’t Afford Not . to Do Things Differently...
Capital Asset Pricing and Arbitrage Pricing Theory
by liane-varnes
Bodie, Kane and Marcus. Essentials of Investments...
Capital Asset Pricing and Arbitrage Pricing Theory
by mitsue-stanley
Capital Asset Pricing and Arbitrage Pricing Theor...

1 FAMA-FRENCH MODEL Concept and Application
by playhomey
Learning Objectives. Concept of . Fama. and Frenc...

Financial Economics By Dr.G.YOGANANDHAM,
by desha
Associate professor & Head,. Department of eco...
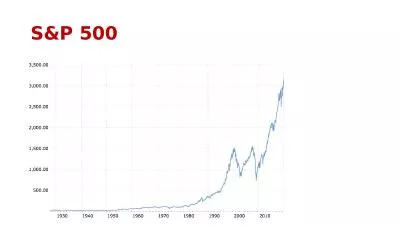
S&P 500 S&P 500, logarithmic scale
by paige
Asset price model assumption. S(t) = Asset price a...




Using SPSS and R for Mediation Analyses
by pasty-toler
Matt Baldwin. Lucas Keefer. We will cover…. Sim...


Counterexample Generation for Separation-Logic-Based Proofs
by myesha-ticknor
Arlen Cox. Samin Ishtiaq. Josh Berdine. Christoph...
THREE NOVEL FACTORS AFFECTING HEDGE FUND RETURNS China Derivatives Market Conference (CDMC)
by lois-ondreau
THREE NOVEL FACTORS AFFECTING HEDGE FUND RETURNS ...
THREE NOVEL FACTORS AFFECTING HEDGE FUND RETURNS
by mitsue-stanley
THREE NOVEL FACTORS AFFECTING HEDGE FUND RETURNS ...

Two Pillars of Asset PricingPrize Lecture, December 8, 2013by Eugene F
by arya
6490_Book.indb 365
11/4/14 2:30 PM
The Nobel P...